Later Life Lending: Advisers Can’t Afford to Sit on the Sidelines
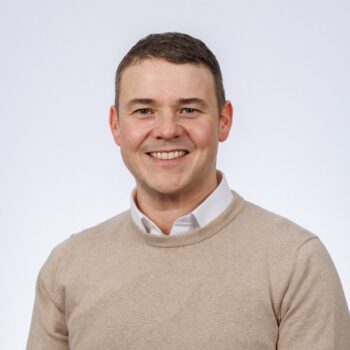
Andrew Needham, our Head of Network Relationships (North), considers the increasing need for mortgage advisers to speak to clients about later life lending, and how to ensure they’re prepared for a valuable conversation.
Why is later life lending becoming harder for advisers to ignore?
Later life lending is no longer a niche conversation sitting on the edge of mainstream mortgage advice. With older homeowners holding significant levels of housing wealth, more clients reaching retirement with borrowing needs, and interest-only mortgages continuing to mature, advisers are going to see more clients whose circumstances do not fit neatly into traditional lending routes. The market may still be relatively small, but its importance is growing and it is becoming an increasingly relevant part of the overall advice landscape.
What client needs are driving the growth of this market?
Clients are living longer, borrowing later, helping family members onto the property ladder, managing debt into retirement, dealing with affordability pressures and looking for more flexibility around how they use their housing wealth. Later life lending is not just about equity release anymore. It can also include retirement interest-only mortgages, standard mortgages into later life, product transfers, remortgage options and wider conversations around financial wellbeing in retirement.
Why are some advisers hesitant to get involved?
In my view, the biggest barrier is confidence. Many advisers understand that later life lending exists, but they may not feel comfortable raising it, explaining the options, or knowing when it should be considered. It can feel more complex because the advice often goes beyond the mortgage itself and brings in family, inheritance, retirement income, vulnerability, long-term care and wider financial planning. That can make advisers cautious, but avoiding the conversation altogether means clients may miss out on advice that could be relevant to them.
Is later life lending still seen as specialist?
Yes, I think it often is. Many advisers still see later life lending as something separate from their day-to-day mortgage advice, rather than something that should naturally form part of a broader client conversation. Not every adviser needs to become a later life specialist, but every adviser should be able to recognise when a client may benefit from exploring their options. The danger is that if advisers continue to view it as “someone else’s market”, they risk being left behind as client needs continue to evolve.
How should advisers approach the conversation?
It starts with asking better questions. Advisers do not need to force later life lending into every conversation, but they should be alert to the signs. Is the client approaching retirement with borrowing still in place? Are they supporting children or grandchildren financially? Are they struggling with affordability? Do they have an interest-only mortgage approaching maturity? Are they looking to release money from their home but unsure of the options? These are all moments where a later life discussion may be appropriate.
What if an adviser doesn’t hold the right permissions?
That should not stop the conversation from happening. If an adviser does not have the qualification or permissions to advise in this area, then having a trusted referral route is essential. The adviser can still identify the need, explain that specialist advice may be appropriate, and make sure the client is introduced to someone who can support them properly. A good referral process protects the client relationship rather than putting it at risk. Within Cornerstone, we have established referral routes in place with specialists who have a vast amount of knowledge in this area. That means advisers can introduce their client with confidence, knowing they will be looked after properly, while the client relationship remains with the adviser.
Why does this matter commercially for advisers?
There is a clear commercial opportunity, but it has to start with client need. Advisers who are able to have broader conversations will deepen relationships, spot more opportunities and provide more rounded support. Later life lending can open up conversations around protection, retirement planning, family support, remortgages and long-term client outcomes. If advisers do not ask the questions, someone else will.
What happens if advisers don’t start talking about later life lending?
The risk is that advisers become disconnected from an area of the market that is likely to become increasingly relevant. Clients’ needs are changing, and the traditional advice model needs to change with them. Advisers who fail to evolve may find that they are no longer able to support clients fully through every stage of life. Those who do adapt will be better placed to retain clients, support families across generations and remain relevant as the market develops.
What is the message to advisers?
Start the conversation. While advisers do not need to have all the answers straight away or become specialists overnight, recognising the growing role this sector plays is increasingly important. With the right support, training and referral pathways in place, firms can build confidence in this area and ensure clients have access to suitable solutions. Advisers who build their understanding and establish the right referral routes early are likely to be better positioned as demand for later life lending continues to grow.